Multipass is a financial services provider offering global business accounts, multi-currency payments, and cross-border transaction solutions.
Read case study
Canada · PSP
A wallet that keeps money for its users maintains accounts and holds funds, two of the five payment functions in the Retail Payment Activities Act. That puts it under Bank of Canada supervision, and once users can send money to each other, usually under FINTRAC as a money services business too.


Multipass is a financial services provider offering global business accounts, multi-currency payments, and cross-border transaction solutions.
Read case study

Paysend & Crassula - a banking solution for international companies
Read case study

LuxPay is at the forefront of providing advanced financial services, designed to meet the needs of modern businesses and consumers alike.
Read case study

Wickie offers secure and scalable fiat and cryptocurrency payment solutions, providing users with digital wallets and seamless financial services across multiple platforms.
Read case study
A CAD wallet for each user, with USD or other currency balances alongside it, and available and reserved amounts kept apart on the ledger.
Users look each other up by phone number or email and pay instantly inside the wallet, with a second factor on every payment.
Several verification levels, each with its own limits, so your compliance officer decides what a user can do before and after identity checks through a connected provider.



User funds sit in your trust or safeguarding account at a bank, and the ledger splits them into named wallets. The CAD connection to that bank is scoped in your project.
Push notifications for every top-up, payment and withdrawal, and two-factor confirmation for the actions that move money.
Each requirement, what the platform gives you for it and who owns it after launch.
A description of each flow, from top-up and holding to payments between users and withdrawal, and where each one runs.
You, with your lawyersThe ledger produces this list for every wallet holder, each day, as an export.
Your finance team, on platform dataOne omnibus account split into named user balances on the ledger. The account and any insurance are arranged by you.
YouBalances and contact details per user that an insolvency administrator can work from.
You, with platform dataA description of the platform, hosting, backups and our incident process, for the third-party part of your framework.
Your senior officer, with our inputDetection and resolution times from our incident process as your technology provider.
SharedDaily totals of user funds, with each user's country on record, ready for the monthly averages.
You, with platform dataA description of the new feature's flows, such as adding cards or a currency, for your notice.
YouVerification levels, identity checks through connected providers and full payment history per user.
Your compliance officer
Rails your customers can use
Rules that change what you have to build, in the order they apply.
Application window for PSPs that were already operating. A new wallet provider now applies through PSP Connect and waits for a decision.
RPAA obligations started. Registered PSPs need working risk management and safeguarding frameworks.
The Bank of Canada began publishing notices of violation by PSPs, so enforcement is now public.
Annual report for 2026 due, with the average end-of-day user funds for each month of the year.
The Bank wants to understand where users' money sits and what happens if something breaks. We give you a live wallet and the technical write-up behind it, and your lawyers handle the RPAA application and the FINTRAC registration.
A configured environment to show the regulator, not slides.
The flow behind each payment function, safeguarding records, hosting, third parties and incident handling, written for your RPAA application and frameworks.
Banking, safeguarding and KYC providers from our network, matched to your registration.
Crassula provides technology and documentation support. We do not provide legal or regulatory advice and cannot guarantee the outcome of an application.

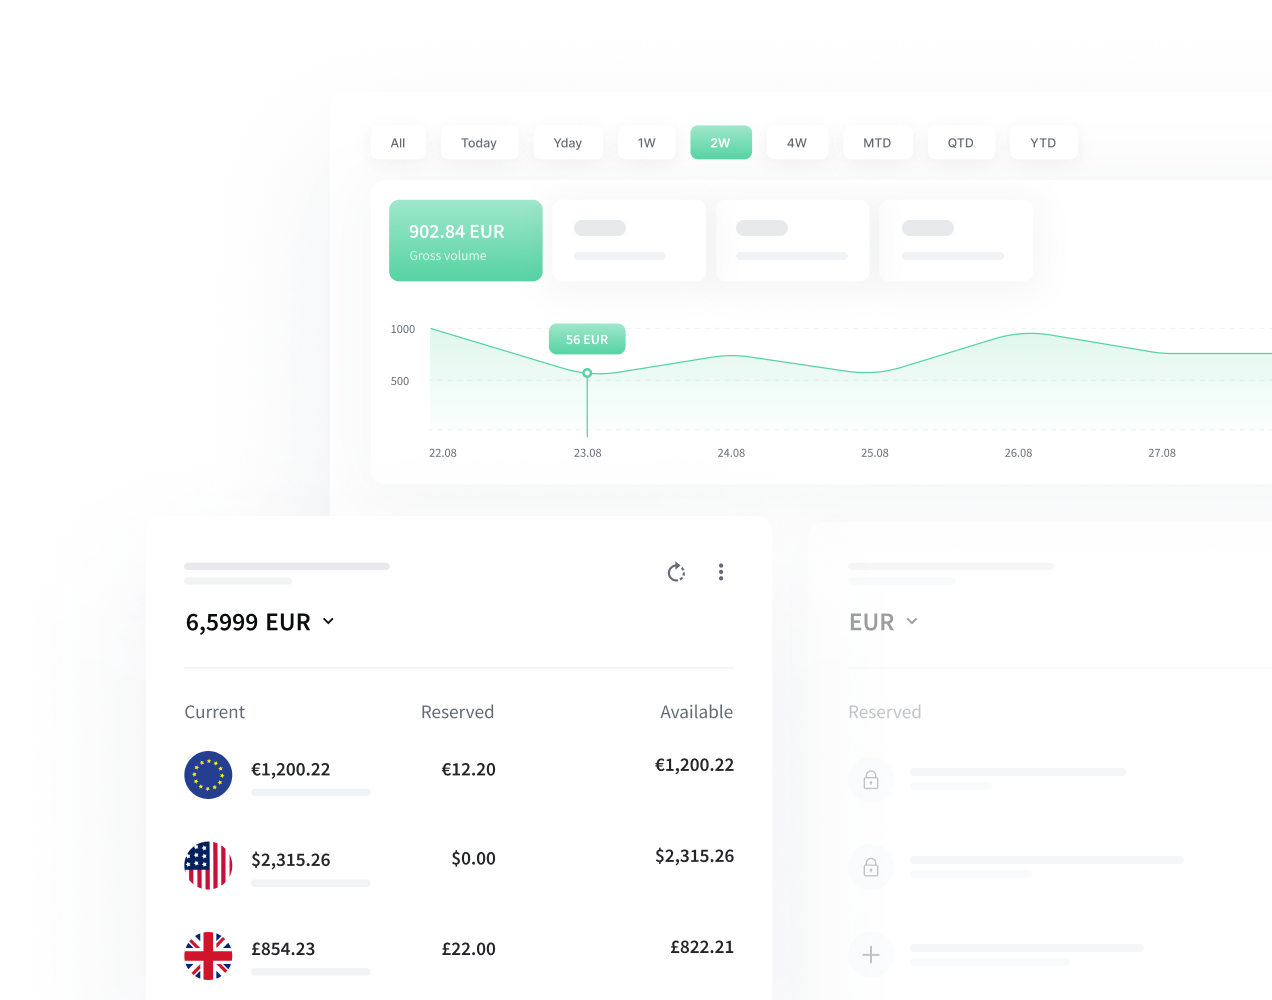
Imagine a Vancouver team building a wallet for international students. Parents send money from abroad, and students pay each other for rent and groceries. The lawyers confirm that the wallet maintains accounts and holds funds, so the team registers with FINTRAC as an MSB and applies to the Bank of Canada.
While the application is reviewed, we set up the wallet in their brand and the team opens a trust account at a Canadian bank. Once registered, students join at a basic verification level and move to higher limits after their ID check. Every evening the platform lists each student's funds with name and contact details, and finance compares the total with the trust account. The daily totals later feed the monthly averages in the annual report.
For the rules, read our RPAA registration guide and the guide to MSB registration in Canada.